

Acima Leasing
by Acima
3.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.8
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
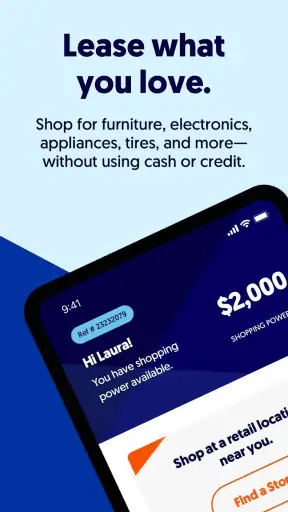
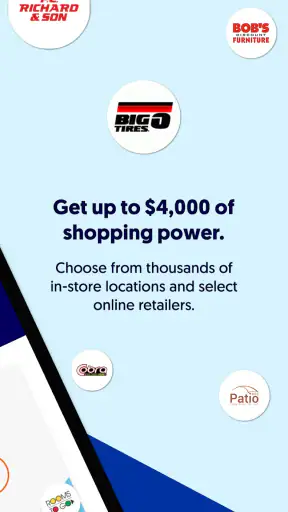
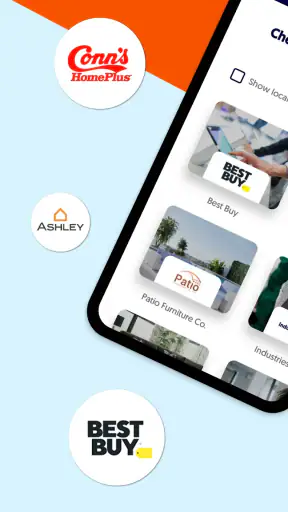
 Analysis by Getfullapps
Choosing a financing app is less about finding the one with the most buttons and more about understanding what kind of purchase problem it solves. I approached Acima Leasing as a practical decision tool for someone who needs an item now but may not qualify for, or may not want, traditional credit. It is a free finance app from Acima, aimed at connecting users with a no-credit alternative to ordinary financing. That sounds straightforward, but the important question is whether this type of lease-to-own approach fits your budget, timing, and willingness to manage scheduled payments.
My overall impression is that the app is most useful when you already have a specific purchase in mind and want to explore an alternative to a standard credit card or loan application. It is less compelling as a general money-management app. You will not open it for budgeting charts, investment research, or everyday banking tools. Its purpose is narrower, and that can be a strength if you need the service it represents.
What to consider before choosing Acima
The first decision is not whether the app looks convenient; it is whether leasing is appropriate for the purchase. A traditional loan usually gives you a defined borrowing arrangement, while a lease-to-own path can involve different payment terms and a different total cost. I would therefore begin by identifying the item, the amount you can comfortably pay over time, and the point at which ownership matters to you.
That last detail is easy to overlook. A payment that seems manageable each month can still make an item considerably more expensive than paying upfront. Before agreeing to anything, I would read the complete offer carefully, including the payment schedule, total amount, ownership conditions, and any options available if your circumstances change. The app can help you start the process, but it cannot decide whether the arrangement is affordable for your household.
Acima is also aimed at people who may have difficulty using conventional credit. That does not mean the service is automatically cheaper, easier, or suitable for everyone with a limited credit history. The useful distinction is access versus value: an alternative may make a purchase possible, while still costing more than saving first or using a less expensive financing method. I see the app as a way to investigate an option, not as a reason to skip comparison shopping.
The practical details are familiar to anyone choosing a mobile finance service. It is a free app for everyone, and it requires Android 7.0 or later. It was released in June 2021 and is currently at version 5.3, so people using an older device should check compatibility before planning around it. The listing shows an average rating of 3.8 from around 4,600 ratings, with more than 2,000 written reviews. That is enough public feedback to suggest a mixed but usable experience rather than universal satisfaction.
I would also separate the app experience from the underlying agreement. A smooth screen cannot make an expensive lease inexpensive, and a frustrating screen does not necessarily mean the offer itself is unsuitable. When using a finance app, I pay attention to both: how clearly the app presents the choices and whether the financial commitment makes sense outside the phone.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
How I would use it in a real purchase
Imagine that a household appliance stops working shortly before payday. Replacing it cannot wait, but a conventional credit application is not attractive or may not be available. In that situation, I would install Acima, review the available path, and use the app to understand what the payment commitment would mean over the full term. I would then compare that figure with the cash price, a retailer’s ordinary financing option, and the possibility of buying a less expensive replacement.
The important workflow is to pause after approval or eligibility information appears. Many shoppers focus on the first payment because it is the easiest number to absorb. I would instead write down the recurring amount, the number of payments, and the total required under the agreement. If an early payoff or purchase option is presented, I would examine its conditions rather than assuming it automatically produces the lowest cost.
A second useful scenario is an urgent work-related purchase, such as equipment needed to continue earning income. Here the decision depends on whether the item is genuinely productive and whether the expected income can cover the obligation without relying on optimistic assumptions. If the purchase is merely desirable, waiting and saving is usually the safer comparison. The app may provide access, but access should not be confused with affordability.
Where the app has a practical advantage
The clearest advantage is focus. Acima is not trying to be a full bank, a credit-score dashboard, or a broad personal-finance suite. Its identity is tied to a no-credit alternative to traditional financing, which makes the intended use easy to understand. If you are specifically looking for lease-to-own financing, you do not have to sort through unrelated budgeting or investing features first.
It can also be useful for people who feel shut out by conventional lending. A traditional credit card may be unavailable, carry an uncomfortable limit, or encourage a revolving balance that is difficult to control. A lease-based arrangement is not a universal replacement, but it gives some shoppers another route to investigate. That is the app’s strongest reason to exist.
Another advantage is portability. A phone-based application lets you begin reviewing the process without sitting at a desktop computer or relying entirely on a store employee to explain every step. I find that valuable because financial decisions are easier to evaluate when I can slow down, reread the terms, and discuss them with someone else before committing.
Its audience is also broad in a basic sense: the app is free to install and carries an Everyone content rating. That makes it approachable for ordinary adult shoppers and households where more than one person needs to inspect the process. Still, an accessible interface does not remove the need for the person signing the agreement to understand the legal and financial responsibility involved.
The app’s public reach is substantial, with over a million installs. I would not treat that figure as proof that every user has had a good experience, but it does indicate that Acima is not an obscure experiment. Combined with the visible ratings and reviews, it gives prospective users a reasonable starting point for checking how the service feels in practice before deciding whether to continue.
Small habits that make the experience safer
My first tip is to use the app before you are under maximum pressure. If a purchase is urgent, people naturally accept the first workable option. Exploring the process earlier, when possible, gives you time to compare the full commitment and avoid making a decision based only on immediate need.
My second tip is to keep a separate record of the agreement. Save the payment dates, total obligation, and any ownership or early-purchase conditions in a place you already use for household bills. A finance app is convenient, but relying on memory or assuming that a notification will always be enough is poor financial housekeeping.
Third, compare the same item rather than comparing vague categories. Look at the cash price for the exact product, then compare the total under Acima and under any conventional financing offered by the seller. This prevents a lower monthly payment from hiding a higher overall cost. It also reveals whether choosing a simpler model would solve the problem without financing at all.
Finally, involve another person when the purchase affects shared finances. A second reader may notice a payment condition or ownership detail that is easy to miss when you are focused on getting the item quickly. I consider that especially important for large household purchases, where the commitment can outlast the initial excitement or emergency.
When another category may fit better
Acima is not the right choice simply because a bank says no. If you can pay cash without damaging your emergency reserve, cash is often the clearest option because it avoids a continuing obligation. If you have access to a conventional loan with transparent terms and a lower total cost, that route may be better too. The app should be compared against those alternatives, not treated as the default winner.
A credit card may suit someone who can repay the balance quickly and has a genuinely favorable promotional arrangement. A personal loan may be more appropriate when you need a fixed amount for a clearly defined purpose and want a conventional repayment structure. A retailer’s own financing may also be preferable if its total cost is lower and the terms are easier to understand. I would judge these options by the complete amount paid, not by the smallest advertised payment.
There is another category difference worth noting: budgeting applications. If your real problem is planning monthly spending, tracking bills, or building savings, Acima will not replace a budgeting tool. Its role is connected to obtaining an item through an alternative financing arrangement. Someone looking for a broad financial dashboard may find it too specialized.
The same applies to users who dislike lease-to-own models on principle. If ownership from the first day is important, or if you want the simplest possible relationship between price and payment, saving first or using a conventional purchase method will probably feel more comfortable. The app can still be informative, but it may not be the best route for the transaction itself.
I would also be cautious if your income changes from month to month. A payment that fits during a strong month can become stressful during a slow one. In that situation, the relevant question is not whether you can make the first payment, but whether you can maintain the obligation during an ordinary difficult month. If the answer is uncertain, delaying the purchase or choosing a cheaper item is safer than relying on future income.
The real cost of switching to this option
Switching from a conventional purchase to Acima is not just a change of app. It changes how you think about the item, because the headline price is no longer the only number that matters. You need to track recurring payments, understand when ownership is obtained, and keep the agreement visible in your monthly planning. That extra mental load is a genuine cost, even if the mobile experience is simple.
There can also be a behavioral cost. A low initial payment may make a purchase feel more affordable than it really is. I would avoid using the app for several nonessential items at once, because separate manageable commitments can combine into a difficult monthly total. One carefully evaluated purchase is easier to monitor than a collection of agreements made under pressure.
There is a switching benefit as well. For someone who cannot use ordinary credit, Acima may reduce the time spent searching for a workable financing path. It may also make an urgent purchase possible when waiting is impractical. That benefit is meaningful, but it should be weighed against the full financial commitment and the possibility that a cheaper alternative requires more patience.
Before moving forward, I would answer four questions in writing: What is the exact item I need? What will I pay in total? What happens if I want to finish early or change course? Can I make every scheduled payment without cutting essentials? If any answer is unclear, I would stop and seek clarification rather than treating the app’s convenience as a reason to continue.
What the ratings and platform details suggest
The rating profile gives me a moderate level of confidence, not blind reassurance. A 3.8 average means plenty of people find the app useful, while others have encountered enough friction to rate it lower. In finance, that is a reason to read recent user comments for patterns involving sign-in, application steps, payment visibility, or communication. Reviews are most valuable when they reveal repeated workflow problems rather than isolated frustration.
Because the developer is Acima, the app is closely tied to the company’s own financing service rather than being an independent comparison marketplace. That can make the journey more direct, but it also means I would not expect the app to present every possible financing product in the market. For broad comparison, I would still check banks, retailers, credit unions, and cash alternatives separately.
Version 5.3 suggests the app has received ongoing updates since its original release. I see that as a positive sign for maintenance, but not as a guarantee that every device or user journey will be flawless. Keeping the app updated and using a secure device are sensible steps, especially when entering personal and financial information.
I would also remember that a free download is not the same as a free financial service. There is no installation charge, but the agreement connected to the app has its own financial terms. That distinction is central to using it responsibly: judge the app by its convenience, and judge the lease by its total cost and conditions.
My recommendation for different kinds of users
I recommend trying Acima if you have a specific essential purchase, conventional financing is unavailable or unattractive, and you are prepared to inspect the complete lease-to-own terms. It is particularly worth considering when timing matters and you need a structured alternative rather than another general finance app. In that situation, the app can be a practical first step toward understanding your options.
I would recommend it less strongly for discretionary shopping, uncertain income, or purchases where you have not compared the cash price with the total payment commitment. I would also steer borrowers with access to a clearly cheaper conventional option toward that alternative. The goal is not simply to obtain the item; it is to obtain it without creating a payment problem that lasts longer than the item’s usefulness.
My final view is balanced: Acima is a focused finance app with a clear audience and a meaningful purpose, but its value depends almost entirely on the agreement behind the screen. I like it as a way to explore a no-credit alternative, especially when other routes are closed. I would not use it casually, and I would never judge the decision by the first payment alone. Use it as a comparison tool first and a commitment tool second. That mindset gives the app its best chance of helping rather than turning an urgent purchase into a long-running burden.
Pros
- Flexible lease-to-own options for users with limited credit history.
- Application process is generally quick and convenient through the app.
- Payment schedules can be easier to manage than paying the full price upfront.
- May provide access to essential household items without traditional financing.
- Account tools help users review payments and manage their lease information.
Cons
- Lease-to-own costs can exceed the item's original cash price.
- Missed payments may trigger fees or affect your ability to keep the item.
- Not every retailer or product may be eligible for Acima financing.
- Terms and total costs require careful review before accepting an agreement.
- Availability and features may vary depending on location and participating stores.
FAQs for Acima Leasing
What is Acima Leasing, and how does it work?
Acima Leasing is a lease-to-own service that may help shoppers obtain furniture, appliances, electronics, tires, and other eligible products when they do not want to use traditional credit. After applying through a participating retailer or the Acima platform, approved customers make scheduled lease payments. Ownership terms, payment amounts, and total cost can vary, so reviewing the agreement carefully before accepting is essential.
Does Acima Leasing require a traditional credit score?
Acima Leasing is generally marketed as an alternative for shoppers who may not qualify for conventional financing, and approval may consider more than a standard credit score. However, approval is not guaranteed, and applicants may still need to provide valid identification, income or employment details, banking information, and other required data. Eligibility requirements can differ by state, retailer, and individual application.
How much does Acima Leasing cost in total?
The total amount paid through a lease-to-own agreement can be substantially higher than the product’s cash price, particularly when payments continue for the full lease term. Acima may offer an early-purchase option that can reduce the overall cost if completed within the stated period. Before signing, compare the cash price, payment schedule, fees, renewal terms, and total ownership cost.
Can I return an item or cancel an Acima Leasing agreement?
Return and cancellation rules depend on the specific lease agreement, the retailer’s policies, the item purchased, and applicable local law. Returning merchandise does not automatically mean every payment or obligation disappears, and missed or incomplete requirements may create additional costs. Contact Acima and the retailer promptly, keep written confirmation, and read the agreement’s return, reinstatement, and cancellation sections.
Is the Acima Leasing app safe to use, and what can I do with it?
The official Acima app or mobile website may allow customers to review account details, monitor payments, access lease information, and manage certain account-related tasks. Download it only from an official app store or Acima’s verified website, and check the developer name before installing. Because the service handles financial and personal information, use a strong password and avoid accessing your account on unsecured public networks.

Acima Leasing
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via appsupport@acima.com, visit https://www.acima.com/, or review their https://www.acima.com/privacy-policy.










